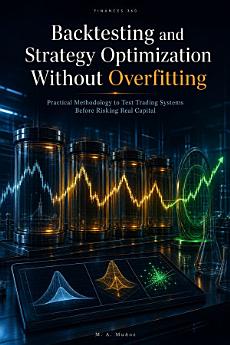
Backtesting and Strategy Optimization Without Overfitting: Practical Methodology to Test Trading Systems Before Risking Real Capital
FINANCES 360
M. Muñoz
eBook
236
หน้า
เครื่องมือ
info
family_home
มีสิทธิ์
info
เกี่ยวกับ eBook เล่มนี้
Most trading strategies that work brilliantly in backtesting fail in real markets. This book explains how survivorship bias, look-ahead errors, excessive optimization, and unrealistic cost assumptions distort results. It covers walk-forward analysis, Monte Carlo simulation, the Deflated Sharpe Ratio, multi-market validation, Python frameworks, and real case studies so traders can test systems rigorously before risking capital. By FINANCES 360.
Most trading strategies that work brilliantly in backtesting fail in real markets. This book explains how survivorship bias, look-ahead errors, excessive optimization, and unrealistic cost assumptions distort results. It covers walk-forward analysis, Monte Carlo simulation, the Deflated Sharpe Ra...
ให้คะแนน eBook นี้
แสดงความเห็นของคุณให้เรารับรู้
ข้อมูลในการอ่าน
สมาร์ทโฟนและแท็บเล็ต
ติดตั้งแอป Google Play Books สำหรับ Android และ iPad/iPhone แอปจะซิงค์โดยอัตโนมัติกับบัญชีของคุณ และช่วยให้คุณอ่านแบบออนไลน์หรือออฟไลน์ได้ทุกที่
แล็ปท็อปและคอมพิวเตอร์
คุณฟังหนังสือเสียงที่ซื้อจาก Google Play โดยใช้เว็บเบราว์เซอร์ในคอมพิวเตอร์ได้
eReader และอุปกรณ์อื่นๆ
หากต้องการอ่านบนอุปกรณ์ e-ink เช่น Kobo eReader คุณจะต้องดาวน์โหลดและโอนไฟล์ไปยังอุปกรณ์ของคุณ โปรดทำตามวิธีการอย่างละเอียดในศูนย์ช่วยเหลือเพื่อโอนไฟล์ไปยัง eReader ที่รองรับ